How Cloud Mining Fits Into a Diversified Crypto Portfolio
A portfolio-construction framework for cloud mining: correlation to BTC spot, sizing within your crypto sleeve, rebalancing rules, and drawdown behavior.
Cloud mining sits inside a crypto portfolio as a correlated-but-not-identical exposure to BTC: it rides the same long-term price wave as spot, but its monthly cashflow is driven by hashprice — a blend of BTC price, network difficulty, and transaction fees. That makes it a sleeve, not a substitute, for coins you already hold. This guide is a framework for deciding how much, where, and when — not a percentage recommendation.
Why portfolio construction matters for cloud mining
Most cloud mining articles either sell it as a "passive income stream" or dismiss it as a crypto bet in a costume. Both miss the point. Inside an allocator's mental model, cloud mining is a distinct return stream with its own risk factors, and the right question is not "should I do it?" but "where does it sit relative to the BTC, altcoin, and stablecoin sleeves I already have?"
That framing changes the analysis. You stop comparing cloud mining to the risk-free rate (unfair — one is a cash equivalent, the other is a crypto exposure) and start comparing it to the alternative uses of the same crypto-dedicated capital: more spot BTC, more altcoin beta, more staking yield, more stables waiting in dry powder. Each has a different correlation, drawdown profile, and tax treatment. A mining sleeve only earns its seat if it does something the others don't.
The rest of this article walks through the four questions an allocator should answer before putting a dollar into cloud mining: how it correlates, how big it should be, how it behaves in a crash, and when to rebalance it.
Correlation: same asset, different return driver
Spot BTC returns are a pure function of BTC/USD price. Cloud mining returns are a function of hashprice, which is BTC price multiplied by per-terahash daily BTC reward, minus the impact of network difficulty. Same directional exposure, very different short-term behavior.
A useful parallel: listed Bitcoin mining stocks historically traded with a beta to BTC of roughly 1.5–2.5 during strong bull regimes and often underperformed BTC in the months immediately after a halving. According to VanEck's 2024 miner analysis, BTC rallied roughly 120% in 2024 while hashprice fell ~75% after the April halving cut block subsidy from 6.25 to 3.125 BTC. BTC price and mining economics can diverge for months at a time.
Cloud mining inherits that same split personality without the equity premium. The rental fee is fixed in USDT; the payout floats with hashprice. In practical terms:
Shared wave
Over 12+ months, cloud mining and spot BTC tend to move in the same direction — both rise in bull regimes, both shrink in real USD terms in deep bear markets.
Different month-to-month
Difficulty adjustments, fee spikes, and halvings mean mining can be flat while spot rallies, or keep accruing BTC while spot chops sideways.
Time-averaged payout
BTC drips every minute across the rental period, smoothing out entry-timing risk that dominates a single lump-sum spot buy.
The last point is the subtle one. A spot buy on the wrong day prints a bad cost basis for years. A 12-month rental averages the effective cost basis across ~525,000 minutes of payouts — you're forcibly dollar-cost averaging into BTC at the hashprice prevailing each minute, whether that's a local top or local bottom.
Where a mining sleeve sits in your crypto allocation
Think of a crypto-dedicated pool of capital as four sleeves with different jobs. Cloud mining doesn't replace any of them — it overlaps with BTC spot on directional exposure but differs on cashflow pattern. A rough taxonomy:
| Sleeve | Primary job | Correlation to BTC spot | Cashflow |
|---|---|---|---|
| Core BTC spot | Long-term store of value | 1.00 (by definition) | None |
| Cloud mining | BTC accumulation + time-averaged entry | High but not 1.00 (hashprice drift) | BTC, per-minute |
| Altcoin beta | Upside amplification, thematic bets | ~0.7–0.9 (varies by coin and regime) | Optional staking yield |
| Stables / dry powder | Drawdown buy-the-dip optionality | ~0 (intentionally) | Stable yield on-chain or off |
The insight that matters: a mining sleeve is partially redundant with BTC spot on direction, but orthogonal on cashflow pattern. If your goal is maximum BTC exposure, spot is more capital-efficient (no management fee drag, no hashprice risk). If your goal is a running BTC income stream without selling spot to harvest it, mining provides that while spot cannot.
That framing is why the sizing decision isn't "what % of net worth goes into mining?" but "what % of the BTC-directional portion of my crypto sleeve do I want delivered as cashflow instead of a static position?" An allocator who already has meaningful spot BTC and wants to harvest some cashflow without selling behaves differently from someone who holds no BTC and is using mining as their first exposure.
How to size the sleeve — a framework, not a number
We deliberately won't give you a percentage. Allocation depends on your total net worth, the share of it you've decided is crypto-appropriate, your income stability, and your tolerance for a sleeve that pays in BTC (a volatile asset) rather than stable currency. What we can give you is the factors that should move that number up or down.
Start from the crypto sleeve, not net worth
Decide the overall crypto allocation first (that's a separate conversation with your financial context in mind). Mining is then a slice of that slice. Sizing it as a % of total net worth mixes two decisions that should be made separately.
Think in terms of monthly USDT commitment, not lump-sum
A mining rental is a recurring USDT cost that should fit comfortably inside your monthly discretionary cashflow — so a deep BTC drawdown doesn't force you to top up from assets you'd rather hold. Rule of thumb: if you couldn't pay the next 3 months of rental from liquidity other than spot BTC, the sleeve is too big.
Scale up with existing BTC conviction
Cloud mining's biggest structural risk is a prolonged BTC bear market. Investors who are already comfortable holding BTC through a 70% drawdown — and the data from Grayscale's diversified portfolio research shows that's a realistic 12-month path in stressed periods — tolerate mining's hashprice compression better than BTC-skeptics using it as their first exposure.
Scale down if cashflow matters more than upside
Mining is not a capital-preservation vehicle. If your primary need from the crypto sleeve is "money I might need in 12 months," stablecoin yield is the right tool. Mining is for capital you're willing to leave exposed for the full cycle.
Start smaller than you think
Run a 1-month rental at the smallest tier first, purely to feel the accrual cadence and the USDT-out/BTC-in bookkeeping. Almost everyone overestimates how comfortable they are with a volatile payout stream until they see their first weekly report during a red week.
Test the cashflow pattern before sizing the sleeve
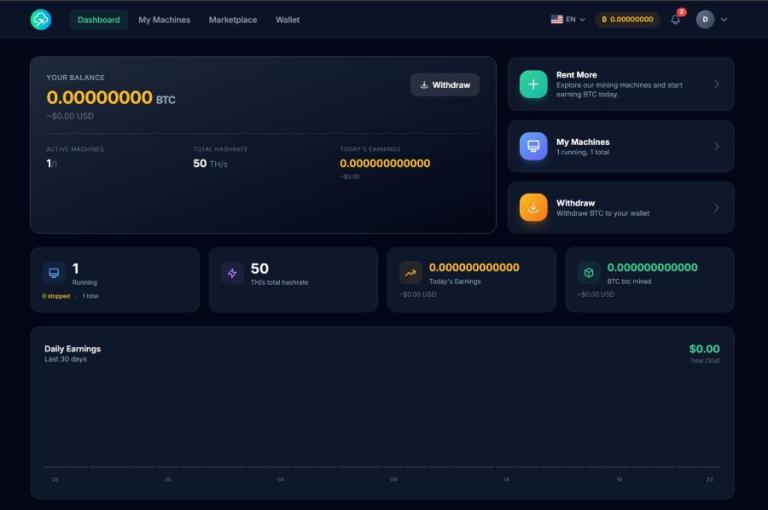
The framework above says start smaller than you think and let the first month teach you how the BTC drip feels. A Basic Miner rental at $20/month is small enough to treat as a research line in your portfolio, not a position.
Drawdown correlation — how the sleeve behaves in a crash
The honest question every allocator should ask: "when BTC drops 50%, what happens to my mining sleeve?" The answer has three layers, and confusing them is where bad sizing decisions come from.
Layer 1 — the USDT rental cost is fixed. You keep paying the agreed monthly fee regardless of where BTC is. A 50% crash doesn't reduce your bill. This is the opposite of spot BTC, where a drawdown reduces the dollar value of your position but requires no further action.
Layer 2 — the BTC payout continues, in BTC terms. The number of sats delivered each minute is governed by hashprice, not by "sentiment." During the 2022 bear, hashprice fell roughly 70% from peak but miners kept producing BTC. Your BTC balance keeps growing during a crash — it's the USD value of that balance that compresses.
Layer 3 — the break-even reference point shifts. The rental was priced assuming a hashprice range. If hashprice compresses below that range for long enough, your effective BTC-cost-per-sat rises above what you'd pay buying spot on the same day. This is the real drawdown risk and it's very different from "BTC went down, therefore my mining went down by the same amount."
Good behavior
The BTC drip doesn't stop during drawdowns. If you measure in sats — not dollars — the sleeve is accumulating fastest when prices are depressed and hashprice is low.
Bad behavior
The USDT cost is sticky. In a deep and prolonged bear (12+ months of depressed hashprice), the cumulative rental paid can exceed the USD value of BTC received. A buy-and-hold spot position doesn't have this failure mode.
Time dimension
Drawdown outcomes depend entirely on how long the bear lasts. Short drawdowns (3–6 months) are a net positive — you accumulate sats cheap. Long ones (12+ months) bend the risk the other way.
Measurement discipline
Track the sleeve in BTC terms (sats accumulated) and USD terms (cumulative rental vs. BTC value). Both matter. Looking at only one hides the real picture.
Rebalancing rules for a mining sleeve
Traditional portfolio rebalancing — sell what's up, buy what's down, restore target weights — doesn't map cleanly onto cloud mining, because the sleeve isn't a liquid position you can trim. You can't "sell 30% of a rental." What you can do is control rental duration, tier, and reinvestment of BTC payouts.
| Market regime | Sleeve behavior | Possible action |
|---|---|---|
| BTC bull run, high hashprice | Mining outperforms spot buy on BTC-per-dollar basis (rental was priced into lower hashprice) | Let current rentals run to term; avoid over-committing at cycle peak pricing |
| Mid-cycle chop | Sleeve performs as expected — steady BTC accrual at fair hashprice | Maintain sleeve; consider longer-term contracts for the discount tier |
| Deep drawdown, compressed hashprice | Most painful period — cost sticky, BTC value of payout falls | Don't scale up on emotion; consider letting short contracts expire without renewal and shifting capital to spot DCA |
| Post-halving normalization | Hashprice often compressed for 6–12 months as block subsidy halves; difficulty re-finds equilibrium | Lean on pre-halving rental pricing; avoid committing large new capital until post-halving hashprice stabilizes |
The most useful rebalancing decision for a mining sleeve is also the simplest: what do you do with the BTC as it arrives? Three common policies:
- Accumulate — BTC sits in the wallet, compounding the long-term core position. Cleanest path, tax-efficient in most jurisdictions because you don't realize gains.
- Self-custody on a threshold — withdraw to hardware wallet each time the balance crosses a set level. Preserves the long-term view and removes counterparty risk from the equation.
- Harvest to USDT on a schedule — convert a set fraction of payouts back to USDT on a fixed rhythm, building the next rental cycle. Essentially self-funding the sleeve after it reaches scale.
Each is a legitimate answer. The wrong answer is not having a policy — drifting between accumulation and ad-hoc selling based on how the price feels that week is how the sleeve quietly underperforms.
Portfolio-construction mistakes we see
Treating it as uncorrelated
Mining and BTC spot share the same long-term wave. If BTC goes to zero, the sleeve goes to zero too. Do not size it as a hedge against BTC itself.
Sizing from projected returns
Starting from "this should return X% so I'll put in Y" is the wrong direction. Returns aren't a commitment. Start from what sleeve size you can live with in a worst-case 12-month hashprice compression.
Funding with sold spot BTC
Selling core BTC to buy a rental is a net-zero BTC exposure move with added cost and operational risk. Fund the sleeve with stablecoin capital you'd otherwise deploy into BTC anyway — not from existing spot.
No policy on the BTC payout
BTC drips in. If you haven't decided in advance whether to hold, withdraw, or harvest, decisions get made emotionally. Write the policy before the first payout, not after.
Frequently asked portfolio questions
Is cloud mining "uncorrelated" with BTC spot?
No. Both depend on BTC/USD. Mining has a different short-term return driver (hashprice vs. spot price), so month-to-month performance can diverge — but over a full cycle the two rise and fall together. Size it as a BTC-directional sleeve, not a diversifier.
Should I use cloud mining as my first BTC exposure?
For most investors, building a small core spot position first is cleaner — fewer variables, no management overhead. Mining works best once you already have BTC conviction and want a running accumulation lane rather than a static position to hold.
How does mining compare to a Bitcoin ETF for portfolio purposes?
An ETF is a static, regulated spot proxy with a 1.0 correlation to BTC. Mining produces actual BTC you can self-custody and adds a cashflow stream, but it comes with hashprice risk the ETF doesn't carry. Different instruments, different jobs.
What's a reasonable review cadence for the sleeve?
Monthly for cashflow check (is the BTC drip arriving as expected, is the USDT outflow comfortable), quarterly for policy review (do I renew rentals, change tier, adjust payout handling). Daily monitoring adds noise without improving decisions.
Does a mining sleeve reduce overall crypto portfolio volatility?
Marginally, mainly because the BTC drip cadence smooths the effective entry price across the rental period. The primary volatility in the sleeve is still BTC-driven, so don't expect it to behave like a stablecoin or bond holding — it's high-beta exposure with a cashflow wrapper.
Not investment advice
This article is a framework for thinking about cloud mining within a crypto portfolio — not a recommendation of specific allocation percentages. Past correlation patterns may not hold; hashprice, difficulty, and BTC price are highly volatile. Cloud mining involves market, operational, and regulatory risk, and returns are never guaranteed. Only commit capital you can afford to leave exposed for the full market cycle, and consult a qualified financial advisor about your personal situation before investing.